Foreign Transaction Fees Explained: How to Avoid Extra Charges When You Travel Abroad

Published:
6 min read
Finsery Editorial Team Finsery Editorial Team

foreign transaction fee

What is a Foreign Transaction Fee?

A foreign transaction fee is charged by your bank or credit card issuer when a purchase is processed outside the country or billed in a foreign currency. Typically ranging from 1% to 3% of the transaction amount, this fee is added to the exchange rate and often appears as a separate line item on your credit card statement, which can make it easy to overlook.

Foreign transaction fees often consist of two parts. One portion should be charged to your card issuer, such as Chase, Capital One, Bank of America, or Citi. The other portion will come from the payment network, including American Express, Discover, Mastercard, or Visa.

Many consumers do not realize this fee can apply even when there is no international travel. You will be charged a foreign transaction fee when shopping on international websites, subscribing to foreign-based services, or purchasing from global marketplaces if a non-U.S. bank processes payment. Even if prices are listed in dollars, the transaction may still be classified as a foreign transaction.

How Do Foreign Transaction Fees Work?

Foreign transaction fees are based on how your payment is processed in the global banking system, not on your physical location. When you use your credit card, the payment is routed through a network like Visa or Mastercard and processed by one or more banks. If any step in this process occurs outside the U.S, your purchase may be treated as a foreign transaction and incur a foreign transaction fee.

Foreign transaction fees may apply under several conditions:

  • When you use your credit card while traveling in another country
    If you buy something in another country, the payment usually goes through a foreign bank and is processed in a different currency. As a result, your credit card company may treat it as a foreign transaction and charge a fee.
  • When you shop online inside the country
    Even if you’re in the U.S., the store’s payment processor or bank might be in another country. If your payment is routed internationally, your card issuer may still charge a foreign transaction fee, even if the price is in U.S. dollars.

Is Foreign Currency the Same as a Currency Conversion Fee?

Foreign transaction fees and currency conversion fees are separate charges. Card issuers apply foreign transaction fees to purchases made outside the U.S., while currency conversion fees apply when funds are exchanged between currencies. Both fees may apply to a single purchase. For example, if you buy an item in a foreign currency, the card network converts the amount to U.S. dollars, and your bank may add a foreign transaction fee. Some merchants offer payment in your home currency, but this often results in a less favorable exchange rate and additional charges. Understanding these fees can help you save money and make informed payment decisions when shopping or traveling abroad.

Why Can You Be Charged Without Traveling Abroad?

Many assume foreign transaction fees apply only when traveling abroad, but they can also apply to purchases made in the United States.

Why can you be charged without traveling abroad

Foreign transaction fees depend on how your payment is processed, not your location. You might see these fees in situations like:

  • Shopping on international websites: Purchases from stores or payment processors outside the U.S. may be processed as international transactions.
  • Paying for foreign-based streaming or software subscriptions: Some digital services and cloud platforms bill through companies located outside the U.S., regardless of where you use them.
  • Purchasing from global marketplaces: Payments to international sellers may be processed through banks outside the U.S.
  • Completing a transaction with a non-U.S. payment processor: Companies using foreign payment systems may classify your purchase as a foreign transaction.
  • Paying in a foreign currency, even online: Payments in currencies other than U.S. dollars typically require conversion by your bank, which may result in a fee.

Finsery pro tip

If you shop internationally, even online, use a credit card without foreign transaction fees. Review your statements to ensure small international charges do not go unnoticed.

How Much Are Foreign Transaction Fees?

Foreign transaction fees are typically a percentage of what you spend. Most U.S. credit card companies that charge this fee use a rate between 1% and 3%. Even though this may seem small, it applies to every international purchase, so the costs can add up quickly.

Here’s an example to show how foreign transaction fees work with common U.S. credit card companies when the fee applies:

Typical Foreign Transaction Fee Breakdown

Bank / Card Issuer Network Fee Issuer Fee Total Fee On $100 Purchase
Captial One - - - -
Discover - - - -
American Express Included ~2.7% ~2.7% $2.7
Bank of America ~1% ~2% ~3% $3
Chase ~1% ~2% ~3% $3
Citi ~1% ~2% ~3% $3
PNC ~1% ~2% ~3% $3
U.S. Bank ~1% ~2% ~3% $3

How Does This Affect Your Spending?

  • If your card has a 3% foreign transaction fee, you will pay an additional $3 for every $100 spent.
  • One international trip or a year of online purchases abroad could result in fees of $50 to $100 or more.
  • Some credit card companies, like Capital One and Discover, don’t charge foreign transaction fees on any of their cards.

These fees apply only if your card charges a foreign transaction fee. Many banks offer travel or premium cards without this fee, which can help you save money when shopping internationally or traveling abroad.

How to Avoid Foreign Transaction Fees?

If you want to avoid foreign transaction fees, choose a credit card that doesn’t charge them. Many travel and rewards cards skip the usual 1% to 3% fee, so you’ll only pay the exchange rate when you buy something abroad. When you travel, pay in the local currency to avoid extra fees, and limit ATM withdrawals to reduce additional fees. Before your trip, check your card’s fee details so you don’t get any surprise charges and can save money.

To avoid foreign transaction fees, use a credit card that does not charge them. Many travel and rewards cards waive the typical 2% to 3% fee, allowing you to pay only the card network’s exchange rate. These cards usually offer the same rewards, protections, and benefits as standard credit cards. Selecting the right card before you travel can help you save on international purchases.

When shopping abroad, pay in the local currency. This lets Visa or Mastercard convert your funds at a competitive rate. Paying in U.S. dollars can add markups. Using local currency increases price transparency and reduces hidden fees.

Dynamic currency conversion happens when a merchant or ATM offers to charge you in U.S. dollars instead of the local currency. While this may seem convenient, it often includes hidden fees. Declining DCC lets your card network process the exchange at a better rate and helps you avoid extra costs.

Withdrawing cash from foreign ATM’s often results in high foreign transaction fees. To minimize costs, withdraw larger amounts less often and plan withdrawals in advance. When possible, use your card for purchases instead of cash withdrawals.

Some banks offer debit cards that refund international ATM fees, helping you save money when accessing cash abroad. If you travel frequently, these refunds can be significant. Before your trip, check whether your bank provides this benefit.

If you plan to travel or shop in another country, take a moment to check the terms for your credit and debit cards. This way, you’ll know about any fees ahead of time. Some cards have foreign transaction fees, but others don’t. Looking over your options now can help you pick the best card for your trip. Staying informed is a simple way to keep your money safe.


Most of the time, you cannot get foreign transaction fees back because they are built into the card’s terms. But you might get a refund if the fee was charged by mistake, if the purchase was wrongly marked as a foreign transaction, or if your card says it does not have these fees. Always call your card company if you see a charge that should not be there.

Can Foreign Transaction Fees Be Claimed as a Tax Deduction?

Foreign transaction fees usually cannot be deducted for personal expenses. However, you may be able to deduct them if they are for legitimate business purposes tied to earning taxable income.

When foreign transaction fees are not deductible

Foreign transaction fees on personal spending are not deductible under Internal Revenue Service (IRS) guidance. This includes fees from vacation travel, international online shopping, or personal subscriptions to foreign-based services. Since these expenses are not related to income-producing activities, they cannot be deducted.

When foreign transaction fees may be deductible

Foreign transaction fees may be deductible if they are directly related to business activities. Fees incurred when paying foreign vendors, purchasing international software or cloud services for work, or covering business travel expenses in foreign currency may qualify as ordinary and necessary business expenses. Currency exchange fees associated with business payments may also be deductible. These fees are typically recorded as bank fees, merchant processing charges, or travel and operating expenses when filing business taxes.

Important note: Foreign transaction fees do not qualify for the foreign tax credit because they are treated as bank service charges rather than foreign income taxes.

Frequently Asked Questions

No, not all credit cards charge foreign transaction fees. Many travel and international credit cards do not charge these fees, including all Discover cards and some Capital One, Chase, and Bank of America cards. If you travel or shop online from other countries, picking cards with no foreign transaction fees helps you avoid paying more.

You may be charged a foreign transaction fee when using your card abroad or buying from international websites and subscriptions processed outside the U.S., even if prices are in U.S. dollars. Sometimes the fee applies because the payment processor is outside the United States.

When you use cards in other countries, credit cards are usually better. They protect you more from fraud, do not take money straight from your bank account, and often do not charge foreign transaction fees. Debit cards may charge these fees, plus extra fees for using ATMs in other countries or banks, so they can cost more when you travel.

Most debit cards charge foreign transaction fees, and these are often higher than the fees for credit cards. Usually, you’ll pay between 1% and 3% for each purchase or cash withdrawal made outside the U.S. or through a foreign bank. If you use an ATM abroad, the operator may charge you $3 to $5, and your bank might also add an out-of-network ATM fee. When you add up these costs, using a debit card overseas can end up being more expensive than using a credit card.

What is a billing cycle and How does it work? A Complete Beginner’s Guide

Updated:
6 min read
Finsery Editorial Team Finsery Editorial Team

What is a credit card billing cycle?

A credit card billing cycle is the period between statements, during which your credit card issuer tallies all your charges, payments, fees, and credits in one transaction. It runs 28 to 31 days, depending on the card issuer, and every primary credit card rule, interest rate, grace period, and reporting depends on this cycle. Think of it as your card’s own financial month, where every transaction you make is recorded to your following statement.

What is a billing cycle and How does it work

Each billing cycle has three anchor points:

1. Billing cycle start date
The day your new billing period begins. Any transaction made after this date belongs to the new cycle.

2. Billing cycle end date or statement closing date
The statement closing date is the day your card issuer finalizes all your transactions for that cycle. Your reported balance is taken on this date, and this balance appears on your credit report.

3. Credit card statement creation
After the statement closing date, your card issuer generates your monthly bill statement. This statement lists all credit card transactions during the cycle and shows the amount you must pay to stay interest-free.

Learning these three key points will help you understand how your spending and payments appear on your credit card statement, how the grace period works, and how your credit score can change.

How do credit card billing cycles work

Each billing cycle begins on a cycle start date and ends on a statement closing date. On the closing date, your issuer generates your billing statement, which shows the balance you owe for that cycle. Here is how billing cycles work step by step.

A new cycle begins the moment the previous cycle closes. Any purchase or payment made from this point is recorded for the next statement. Each month allows you for renewal and a fresh start.

Throughout the billing cycle, your issuer tracks all the transactions you make with your credit card. Everyday purchases, payments, refunds, credits and balance transfers can quickly add up. The running total, or new balance, appears as the statement balance.

The closing date is the key date in your billing cycle, as your issuer records your balance on this day. This due balance becomes your statement balance and is reported to credit bureaus. A high balance on the closing date increases your credit utilization, even if you intend to pay it off the next day.

Your statement will be generated shortly after the closing date. It will show your total balance, minimum payment due, and the due date. Once the statement is issued, the amounts listed will not change.

The payment window opens when your statement is generated and closes on the due date. Paying your full statement balance during this time keeps your purchases interest-free under the grace period.
Many people misunderstand this rule. The grace period applies only if you paid your previous statement balance in full. If you carry any balance into the new cycle, the grace period is lost and new purchases accrue daily interest. Paying on time does not prevent interest charges if the previous cycle was not paid in full.

Statement closing date vs Payment due date

Many beginners confuse the closing date and payment due date, often assuming only the due date affects interest charges and credit scores. In fact, each date serves a distinct purpose and impacts your credit differently. The statement closing date marks the end of your billing cycle, while the payment due date typically occurs three to four weeks later.

Statement Closing Date Overview

This is the date your card issuer finalizes your monthly billing. It determines the following:

  • The statement balance.
  • The reported credit utilization.
  • The status of the grace period.
  • The amount officially billed for the cycle.

Payments made before the closing date reduce your reported balance. Purchases made just before the closing date decrease your interest-free period.

Payment Due Date Overview

The due date is the deadline to pay the amount owed from your statement. It determines the following:

  • Whether you avoid late fees.
  • Whether you avoid a penalty APR.
  • Whether you paid in full within the grace period.

The due date does not impact your reported utilization for the month, as credit bureaus receive account data based on the closing date.

The table below summarizes how these two dates affect your credit, interest, and payments.

Category Statement Closing Date Payment Due Date
Primary purpose Finalizes all activity for the billing cycle Deadline to pay the amount shown on your statement
Impact on credit score High. This balance is sent to credit bureaus None. Reporting is already done
What gets locked in Statement balance, utilization, reported balance, grace period status Nothing gets reported on this date
Effect on interest Decides if next cycle purchases remain interest free Decides if you keep your grace period by paying in full
Pay before this date Lowers your reported balance and utilization Prevents late fees, but does not change your reported balance
Pay after this date No change to what was reported Still required to pay full statement amount to avoid interest
Risk of missing it High utilization recorded for the month Late fees, penalty APR and loss of grace period
Core role Controls reporting and credit score outcomes Controls penalties and interest outcomes

Financial Impact of Confusing these Two Dates

Many people wait until the due date to pay, believing this is sufficient. However, if the closing date passes with a high balance, reported utilization increases, and even a small remaining balance can end the grace period. As a result, interest may be charged even if payment is made on time.

Simple Rules for Paying Credit Card Bills

If you care about your credit score:
Pay before the closing date.
If you care about avoiding interest:
Pay the full statement balance by the due date.

Understanding the difference between these two dates is the key to control your credit card completely

How billing cycles affect your interest and credit score

Your credit card billing cycle is more than just a monthly statement period. It sets the timing of when interest begins, the length of your grace period, and which balance is reported to the credit bureaus. If you know how these parts work together, you can avoid unexpected interest charges and maintain a better credit score with the same spending habits.

How billing cycles affect your interest and credit score

Here are the six most important ways your billing cycle affects both interest and your credit score.

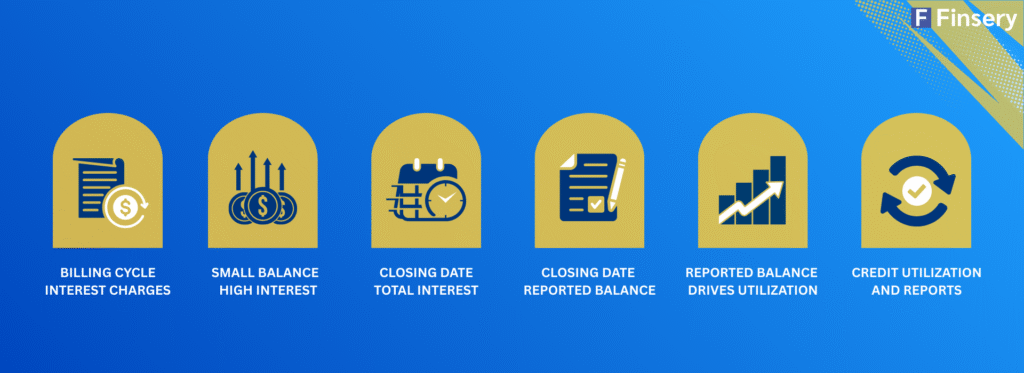
1. Billing cycle controls when interest charges are applied.

Most credit cards offer a grace period that lets you avoid interest on purchases if you meet specific conditions. If you pay your previous statement balance in full, new purchases are typically interest-free until the next due date. If you carry a balance into the next cycle, your issuer may remove the grace period, and interest may begin accruing immediately, even if you make timely payments.

2. Keeping a small balance increases interest charges.

If you do not pay your full statement balance, your next billing cycle will likely be more expensive. The issuer may begin charging daily interest immediately, which can apply to both the remaining balance and new purchases. As a result, you may see interest charges even if you paid by the due date but did not pay the entire statement balance.

3. Statement closing date affects total interest accrued.

Interest is usually calculated using the average daily balance method, which takes into account changes in your account balance during the billing cycle. Higher balances lead to higher interest charges. Payments made after the statement closing date are applied to the next cycle and do not reduce current interest. To minimize interest charges, make payments earlier in the billing cycle rather than waiting until the due date.

4. Closing date determines which credit bureaus receive reports.

Many people assume credit reports are updated based on the amount owed on the due date, but this is not usually the case. Credit card issuers generally report your balance to Experian, Equifax, and TransUnion shortly after the statement closing date. Therefore, the balance on your closing date often appears on your credit report, even if you pay it off in full a few days later.

Finsery Pro Tip

Treat the statement closing date as the effective due date. Paying the full balance before the cycle closes preserves the grace period, reduces reported utilization, and ensures your account is interest-free.

5. Credit balance affects utilization and your score.

Your credit utilization ratio is calculated by dividing your credit card balance by your credit limit. Significantly, the reported balance usually depends on the statement closing date, not the payment due date. If you make your payment after the closing date, your credit card statement may show a high balance, even if you pay in full before the payment due date. This timing can cause your utilization to spike and drag your credit score down. That’s why people with perfect payment history may still see score drops: the balance is reported as high before the payment posts.

6. Timing of credit utilization updates on credit reports

Credit utilization does not update immediately after you make a payment. The Consumer Financial Protection Bureau (CFPB) explains that your utilization is based on the balance reported by your credit card issuer to the credit bureaus. Most issuers report balances once per billing cycle, typically around the statement closing date, so your most recent payment may not be reflected right away. The reported balance appears on your credit report and is used to calculate your utilization ratio, which can affect your credit score.

As a result, even if you pay your card balance to zero today, your credit report may still show high utilization until the next statement closes. The updated balance will appear after your issuer reports it to the credit bureaus, and your credit report gets updated.

A Lesson Ethan Will Always Remember

Ethan didn’t need a new credit card or a “credit hack.” He simply learned one key rule: timing matters as much as paying.

Once he understood his billing cycle, statement closing date, and due date, interest charges stopped, and his balance started reporting the right way. When you know your cycle dates, you gain control over your credit card, not the other way around.

At Finsery, we believe financial success isn’t built on shortcuts. It’s built on understanding the rules and using them confidently.

Frequently Asked Questions

Yes, your credit card billing cycle can change if your issuer updates your account terms, changes your statement date, or if you request a new due date. A billing cycle change can affect when your statement closes, when interest is calculated, and when balances get reported to credit bureaus.

No, paying early doesn’t change your payment due date. It simply reduces your current balance before your statement closes or before the due date arrives. Early payments are still helpful because they can lower your reported balance and credit utilization.

Even if you pay the full balance, you may still be charged interest if you missed the grace period earlier, your payment is posted after the statement closed date, or you had a small balance from the last cycle. So, even if you pay on time, your payment timing and grace period rules can still trigger interest.

Paying your credit card before the statement closes can be very helpful. When the statement is created, your balance will be lower or even zero, so the credit bureaus see a smaller amount owed. This keeps your credit utilization low and can boost your credit score more quickly. It’s a great way to build or fix your credit.
For most people, making payments every week or two is usually better than paying just once a month. This approach helps keep your balance low, stops your credit utilization from getting too high, and reduces the risk of interest if you sometimes carry a balance. Monthly payments can still work well if you always pay in full, but paying more often is often easier for budgeting and helps keep your utilization in check, especially if you use your card a lot.

Not directly, making the minimum payment on time helps protect your payment history. However, paying only the minimum can keep balances high, which can increase your credit utilization ratio and lower your credit score.


What is a credit score and How a good score can help you save money?

Updated:
5 min read
Finsery Editorial Team Finsery Editorial Team

Alex consistently paid his credit card bills on time, often early. Despite this, his credit score dropped by 28 points in one month. The decrease was not due to a late payment, but rather how closing a credit card statement impacted his score.

This example highlights that many people are unaware that their credit score is affected by more than timely payments. Your credit score continues to influence lending decisions, even if you pay your bills on time.

What is a credit score?

A credit score is a three-digit number that indicates a consumer’s likelihood of repaying borrowed money on time. According to the Consumer Financial Protection Bureau (CFPB), the credit score scale ranges from 300 to 850, with higher scores indicating lower credit risk.

In other words, the definition of credit score can be narrowed to a trust factor. The banks and credit card companies rely on your credit score to make a yes or no decision on lending you money, based on which they will charge you an interest rate.

One of the most widely used credit models is the FICO credit score, which nearly all lenders in America currently use for credit card, personal loan, and mortgage lending.

How is a credit score calculated?

The credit score calculation used by FICO follows a consistent formula. While the exact math isn’t public, the credit score percentage breakdown is well known.

Credit score factors (FICO Model)

Factor Weight Impact Level
Payment history credit score 35% Very High
Credit utilization ratio 30% Very High
Credit history length 15% Medium
Credit mix meaning 10% Low
New credit inquiries 10% Low

Together, these credit score components form the foundation of your score.

This is the most important factor and answers a straightforward question: Do you pay on time?

    • Late payments may remain on your credit report for seven years.
    • According to Equifax, even a single 30-day overdue payment can significantly lower your credit score.
    • Paying at least the minimum by the due date protects your credit score.

Consistency is more important than perfection when it comes to credit cards.

Your credit utilization ratio measures the percentage of available credit you’re using.
Example: $2,000 balance on a $10,000 limit = 20% utilization

What many beginners miss:

    • Utilization is calculated when your statement closes, not when you pay.
    • Even with low overall usage, high utilization of a single card can hurt badly.

One of the quickest ways to increase a credit score is by keeping utilization below 30 percent, ideally below 10 percent.

The length of your credit history makes up about 15% of your total FICO score. It shows how long you have been using credit.


The average age of all your credit accounts shows how consistent your credit use has been. When you open a new credit card, your average account age goes down for a while, no matter how well you pay your bills. Closing older cards can lower your average account age even more, especially after those closed accounts drop off your credit report. While no-fee credit cards can help you have a mix of credit types, you should think about how opening or closing accounts might affect your average account age.

Credit mix is approximately 10% of your overall FICO score and refers to the types of credit that you manage. These can include credit cards, auto loans, and mortgages. A credit mix can be favourable if you manage various kinds of credit. A high percentage of bad credit can significantly impact your credit score.


However, you don’t need each type of credit to have a healthy credit score. Many consumers can attain top-notch credit scores by using only credit cards, especially at a younger age when you are initially starting your credit experience. The type of credit you have becomes relevant later, once you are established with a strong payment history and using your credit accordingly.


A better strategy for both beginners and experienced borrowers is to use credit cards responsibly instead of taking on new credit to improve their credit mix.

Inquiries for new credits also constitute about 10% of your credit score. Whenever you apply for a credit card or a loan, your lender performs a hard inquiry on your credit report.

Key points to know:

    • Just one query can reduce your score by a few points.
    • Several applications within a brief time frame can imply a higher risk for the lender.
    • Equifax states that hard inquiries may stay on your credit report for two years; however, the effect reduces with time.

It’s especially important to space out applications when establishing credit for the first time. It will help to protect your score and increase your chances of being approved for other credit cards in the future.

Credit score ranges explained

Credit score ranges help you understand what your score means and how lenders may view your application. Most credit scores fall between 300 and 850, with each range reflecting a different level of risk to the lender. When you know where your score stands, you gain an advantage because a higher score usually leads to better approval chances, lower interest rates, and higher credit limits.

Credit Score Range What It Means
300–579 Poor
580–669 Fair
670–739 Good
740–799 Very Good
800–850 Excellent

If you’re wondering what a good credit score is, most lenders consider 670 or higher to be good credit.

A high credit score typically means lower APRs, higher credit limits, and greater flexibility when applying for loans or buying a home.

How credit cards help you build credit

Credit cards are among the most effective ways to build credit because they report their activity to credit bureaus monthly. Compared to taking out a loan, using a credit card will give you multiple months to show responsible behavior, which will affect your credit score.

Credit scores can be built by focusing on the following basics:

  • Pay on time, every time: Making payments on time can improve your payment history, which is the most significant factor that determines your credit scores.
  • Keep balances low: Keeping balances low reflects positively on your ability to manage credit responsibly without overusing it.
  • Use cards frequently, but lightly: By charging small amounts regularly. This will keep accounts active and establish a positive credit history.

These habits are effective whether you are new to credit, building your credit, or rebuilding it. Properly managed credit cards establish a positive credit history, which also improves your credit score.

Finsery Pro Tip

If you want your credit score to rise faster, make a payment before your statement closing date, not just before the due date, because bureaus score you based on the balance reported on the statement. Keeping the reported balance around 10% utilization often performs better than reporting a high balance.

How long does it take to build credit?

If you are wondering how long it takes to establish credit scores, the key factor is consistency, not speed. Credit scores reflect patterns of behavior over time, and lenders value predictability and steady financial habits.

Generally, people perceive progress in levels:

  • 3-6 months: The process of acquiring a credit score will begin when your first credit card or loan is reported to a credit bureau. In this level, a single payment can help, though you might see your credit scores increase a bit.
  • 6–12 months: By making on-time payments and maintaining a low credit utilization rate, you will see improvements. This is the point at which many people work to improve their credit scores to be eligible for better entry-level credit cards.
  • 12–24 months: Your credit record will become more stable as the average age of your accounts increases and your usage patterns are established. Creditors will then view you as a less risky borrower.

At this stage in your credit journey, you may qualify for lower-APR credit cards, higher credit limits, and better rewards programs. While there is no quick fix, credit scores can improve more quickly than expected with the right habits. Consistent use of credit cards and responsible payments are essential for long-term success. Building credit takes time, so remain patient and consistent. Steady progress is more effective than rushing.

Credit scores aren’t built by shortcuts — they’re built by consistent habits that get reported month after month.

— Finsery Editorial Team

How to improve your credit score

If you want to know how to improve your credit score in a hurry, you need to begin by implementing strategies that impact the most significant credit-score-weighting factors. Although you can’t do it overnight, consumers who use credit cards can implement changes that create a positive impact within a few statement cycles.

The three best approaches are:

  • Paying down credit card balances to lower your credit utilization ratio has a significant impact on your credit score
  • Avoiding new credit inquiries unless necessary, since multiple applications in a short time can slow score growth
  • Keeping older accounts open to protect your credit history length and maintain stability

Paying in full reduces usage and prevents interest from accruing. Rapid credit score increases can be achieved through clever, low-risk behavior.

Credit Building is a Pattern, Not a Shortcut

Alex got the solution
  • Having good credit isn’t about shortcuts; it’s about making habits. Paying your bills on time and keeping small balances on your credit cards are key to improving your credit scores.
  • That was the point that Alex was taught. He came to understand that it was not the time he paid the bill but rather the balance reflecting when the statement closed. The solution was to pay before the statement date, and thus Alex’s score steadied.

Frequently Asked Questions

Even if you paid on time, your score can drop if your reported balance increases. Credit card issuers usually report your balance around the statement closing date, so if the statement closes with a higher balance, your credit utilization ratio rises, and your score may temporarily decrease.

Yes, paying early helps lower the balance before it gets reported, which reduces your credit utilization. Lower utilization generally supports a better score, especially if you bring your balance down before the statement closing date.

To avoid fees and interest, the due date is the most crucial consideration. However, for improving your credit score, the statement closing date matters more because your utilization is primarily based on the balance reported at statement closing, not what you pay later

Your current balance changes daily as you spend and pay. Your statement balance is the amount recorded on the statement closing date. Since issuers typically report monthly statement information, the statement balance often has the most significant impact on your reported credit utilization.

No, checking your own credit score is a soft inquiry that does not lower your score. Only hard inquiries, such as applying for a credit card or loan, can slightly affect your score.

Most credit card companies report to the credit bureaus once per month (at the end of the billing cycle). This is why the balance shown on your statement is often the one reported. The Consumer Financial Protection Bureau (CFPB) explains that credit card periodic statements include the billing cycle closing date and the balance information for that cycle.

Not necessarily, but it isn’t always ideal. If your cards consistently report a $0 balance, scoring models may not see active credit usage. Many consumers achieve better results when a single card reports a small balance, usually around 1%–9% utilization. According to Experian, having an active credit card account with low utilization can be better for your FICO Scores than having no utilization at all.


What Happens if I Miss a Credit Card Payment? How to Avoid Long Term Damage

Updated:
3 min read
Finsery Editorial Team Finsery Editorial Team

If you miss a credit card payment, things can change faster than most people expect. Late fees show up, interest increases, and your credit score may drop if the missed credit card payment isn’t resolved quickly. Even skipping just the minimum payment can lead to penalty APR, lost rewards, and a long-term impact on your payment report.

What Happens if I Don’t Pay My Credit Card Bill on Time?

Failing to pay your credit card payment on time, not even the minimum payment due, results in your issuer reporting it as late. That one missed payment may result in late fees, additional interest, and even credit scarring if not resolved promptly. So many people think it’s fine to pay the full balance later, but as far as penalties go, dropping off a minimum payment on time is better than adjusting your credit card payment due date to pay in full later.

Missed credit card payments can also result from simple misunderstandings, such as assuming you had autopay set up, the check being cut after the cutoff time, or a partial payment made in the belief that it would pass as on time.

Immediate Consequences of a Missed Credit Card Payment

Once a credit card payment is missed, your account can shift in many ways that increase fees, interest, and overall borrowing costs. Here are the most common consequences.

1. Late Fees and How Much They Can Cost You

The first thing you may notice following a missed payment is the credit card late fee. This, depending on your issuer, can be a modest charge; if the incident occurs more than once, a higher fee can apply. If the balance goes unpaid, interest may also be charged on the fee itself.

2. Higher Interest and Penalty APR

Another common consequence is a higher interest rate. Many lenders apply a penalty APR after a missed credit card payment, especially if it isn’t the first. This new rate can replace your standard rate. It may even cancel promotional offers, including 0% intro APR deals, because the penalty rate can be much higher than the regular credit card interest rate.

3. Loss of Rewards and Perks

A missed credit card payment can also impact the benefits associated with that account. Cashback earnings are halted, travel insurance and purchase protections no longer apply, and some rewards programs are put on temporary freezes until the account is back in good standing. For users who rely on perks or point accumulation, losing these benefits can feel just as frustrating as the financial penalties.

How Missing a Credit Card Payment Affects Your Credit Score

Missing one credit card payment doesn’t just affect fees and interest; it also hurts your credit score. Because on-time payments are a key factor in your credit score, a late payment can signal risk to lenders and lower your score.

  • If you have a good or excellent score, a single 30-day late payment could result in a drop in the ballpark of ~60–110 points, depending on your overall credit health.
  • If your credit was a more modest score, or you’ve had other negative marks already, the impact may be less severe, sometimes just a few dozen points, because the score has less “good history buffer” to lose.
  • Over time, with consistent on-time payments and responsible credit use, you can recover much of the damage. However, the initial drop still makes a significant difference, especially if you apply for a loan or financing soon.
  • According to the Consumer Financial Protection Bureau (CFPB), A missed credit card payment can remain on your credit report for up to 7 years even if you’ve paid off the balance.
  • That impact, however, fades over time, especially if you make all future payments on time.
  • Even if the late payment is removed from your credit score, lenders may still see it in your application history, and that can influence whether you’re approved and what interest rate you’re offered.

Payment history is the crucial factor in most credit scoring models. One missed payment indicates a higher risk to lenders. Repeated missed payments do a lot more damage than a one-time slip and make recovery even slower.

How to Recover After Missing a Credit Card Payment

A missed credit card payment can be stressful, but it is not permanent. Taking prompt action helps you manage the impact and return to good standing. By following the right steps, you can protect your credit and prevent further issues.

  • Pay at least the minimum balance as soon as you can. This helps keep your account from slipping further behind and may reduce extra charges.
  • Call your card issuer and ask for a late fee waiver. Many issuers will waive the fee if you normally pay on time, especially if it’s your first missed payment.
  • Freeze new spending on that card. Try to avoid increasing the balance while you catch up and regain control.
  • Ask about hardship programs. Some issuers offer temporary lower interest rates or reduced payments.
  • Convert purchases into EMI’s:
    At checkout: Choose EMI as the payment option and select your preferred tenure.
    After purchase: Convert eligible transactions into EMI via your bank’s app, SMS, or customer support.
  • If it seems like too much to balance, then it’s better to consult a qualified credit counsellor.
  • Build consistent on-time payment habits. Set reminders, adjust autopay settings, or schedule payments early, whatever works for you.
  • Keep your credit utilization low. Ideally, under 30% of your available limit. This helps improve your credit score while you continue to pay off credit card debt.
  • Avoid applying for new credit right away. Hard inquiries and new accounts can temporarily lower your credit score while it’s still recovering.

Frequently Asked Questions

According to Azcourts, a credit card payment is usually reported as late only after it is 30 days past due. Payments missed by less than 30 days may trigger fees or interest, but they don’t affect your credit report.

A credit card payment is considered late only if it is not received by 5 p.m. on the due date, or by 5 p.m. on the next business day if the due date falls on a weekend or federal holiday, as defined by the Consumer Financial Protection Bureau.

Yes, a bank can reduce your credit limit after a missed payment, especially if it happens more than once. This can also increase your credit utilization and lower your score further.

Not usually after one missed payment, but repeated late payments can lead to account restrictions or closure. Issuers review payment patterns before closing the card.

Yes, if payments continue to go unpaid, the account may be sent to collections and could potentially lead to legal action. One missed payment alone typically does not.

A grace period is the time between your statement closing date and the payment due date when interest may not apply. It doesn’t protect you from late fees if you miss the due date.


What is a Credit Card and How Does It Work? A Simple and Reliable Guide

Updated:
6 min read
Finsery Editorial Team Finsery Editorial Team

Credit Card 101: Basics You Must Know

Credit cards can be incredibly useful when you understand how they work. They offer convenience, protection, and a real chance to build strong credit, but misuse can hurt your finances fast. At Finsery, we focus on helping you use credit cards the smart way, so you keep control of your money, not the other way around.

What is a Credit Card?

A credit card is a financial tool that lets you borrow funds from your bank for purchases, bill payments, or cash withdrawals. The bank assigns a credit limit, which is the maximum amount you can spend. You may use the card up to this limit and repay the borrowed amount in full or over time.

How Do Credit Cards Work?

Understanding how a credit card works may seem straightforward, but the details are important. While the basics are simple, how a card operates can determine whether you build a strong credit record or accumulate debt. Finsery aims to provide clear explanations so you can use your card with confidence.

What is credit card

Application and Approval

Before an issuer approves a card, there is a brief check regarding your financial stability. They consider a review of your credit score, your income, any loans or debts you might have outstanding, and how consistently you have made bill payments. This helps the issuer decide if you are eligible for that particular card and what your credit limit will be.

After the approval, the Bank sets your credit limit-it states how much you’re allowed to borrow. Generally speaking, if your credit history is clean and your income is stable, you’ll qualify for higher limits and better card options.

Purchases

When you use your card, the bank pays the merchant instantly on your behalf. You now owe that amount to the bank. When you swipe your card in a store or enter the card details online, three parties work behind the scenes. The payment network you’re using (Visa, Mastercard, American Express, or Discover) redirects and verifies the payments, the merchant receives the money, and your card issuer records the transaction on your account. Once the transaction is approved, the amount you spent is deducted from your available credit.

Billing Cycle and Interest-free Use

  • Every credit card runs on a monthly billing cycle that lasts roughly 28 to 31 days. The cycle starts on your account’s opening date and ends on the closing date, when your card issuer reviews all your spending that month and finalizes your statement.
  • When the cycle closes, your issuer sends a statement that outlines everything you need to know for the month. This statement includes your total balance, the minimum payment due, your interest rate, the due date, and a full list of your purchases.
  • Each month, you decide how much to repay. You may pay the full balance, a partial amount, or the minimum required. Interest applies to any remaining balance.
  • The best way is to pay your full statement balance during the grace period. By doing so, you avoid interest charges on purchases.

Interest and Fees

  • Interest is the cost of borrowing money on your credit card. An Annual Percentage Rate (APR) is applied to any part of your balance that you don’t pay off. If you don’t pay the full balance, the leftover amount starts accruing interest.
  • Most credit cards in the US come with pretty high APRs of 20 to 30 percent, depending on your card and credit history. Since the interest compounds, even small balances can turn into an enormous debt before you know it.
  • Fees are extra charges your card issuer adds only in certain situations, such as paying late, taking a cash advance, or spending past your limit. They’re easy to avoid, but if you’re not paying attention, they can build up faster than you’d expect.

Credit Limits and Utilization

  • The amount of credit you have and your credit utilization significantly affect your credit score. High utilization lowers your score, so aim to keep your credit card balance below 30% of your limit. Paying part of your balance before the statement closing date can also help improve your score.
  • On-time payments are the most important factor in building a strong credit score. Paying your credit card bill on time, even if only the minimum amount, protects your credit score. Consistent on-time payments and low utilization support long-term financial health.

Credit Card Rewards

Credit card rewards offer bonuses each time you make a purchase, such as groceries or fuel. Some cards provide cashback that you can use as you wish, while others let you earn points or miles redeemable for flights, hotel stays, gift cards, or statement credits. To maximize these benefits, choose a card that matches your spending habits and pay your balance in full each month. This approach allows you to turn everyday purchases into added value with minimal effort.

Finsery Pro Tip

Pay down the card before the statement closing date. It lowers the balance that gets reported, keeps utilisation cleaner, and directly impacts the credit score. It’s one of the easiest ways to avoid showing up as high-risk on your credit report.

Credit card vs Debit card vs Charge card

Understanding the differences between credit, debit, and charge cards is essential for effective financial management. Although these cards appear similar, they operate differently and impact your finances, spending power, and credit score in distinct ways. Knowing how each card works will help you select the best option for your financial goals.

Feature Credit card Debit card Charge card
Where funds come from Borrowed from bank/issuer up to a credit limit Directly from your bank account balance Temporarily borrowed funds that must be fully repaid each month
Monthly Payments Can pay in full or pay minimum and carry a balance No monthly payments (spending deducted instantly) Full payment is required monthly with no option to carry a balance
Interest Charged if you don’t pay in full (APR applies) No interest (your own money) No interest, but late fees can be very high
Spending Limit Fixed credit limit set by issuer Your bank balance determines limit Usually no preset spending limit, varies by usage history
Impact on Credit Score Builds or damages credit score depending on use Not reported to credit bureaus in most cases Builds credit score with responsible payment history
Rewards & Benefits Offers rewards like cash back, points, and miles Limited or no rewards Strong premium rewards, travel perks, business benefits
Fees Possible annual fees, late fees, cash advance fees Low fees, mainly ATM charges Often higher annual fees
Best For Building credit & earning rewards Everyday spending & budgeting High spenders and business users

Types of Credit Cards

Card Type Primary Benefit
Cash Back Cards Earn a percentage back on everyday spending, redeemed as cash or statement credits.
Travel Rewards Cards Collect miles or points toward flights, hotels, and travel perks.
Student Credit Cards Help students establish credit early with simpler approval requirements.
Secured Credit Cards Build or rebuild credit using a refundable security deposit as your credit limit.
Business Credit Cards Manage business spending, earn rewards on business expenses, and keep personal and business finances separate.
Low-Interest Cards Reduce the cost of carrying a balance with a lower ongoing APR.
Balance Transfer Cards Move existing debt to a low or zero APR offer to pay it down faster.
General Rewards Cards Earn flexible points you can redeem for travel, merchandise, or statement credits.
Store Credit Cards Get discounts, exclusive offers, or promotional financing at a specific retailer.

Why Credit Cards Can Be Powerful Financial Tools

Credit cards offer important financial benefits when used wisely. They boost your purchasing power and help you build overall financial stability. By using a credit card responsibly, you can earn rewards and cash back, as well as build your credit.

Making payments on time improves your credit history and raises your credit score. This can lead to better loan offers and lower interest rates. Many rewards credit cards give you 1%-5% percent cashback on everyday purchases, allowing you to gain real value for the money you already plan to spend.

Common Credit Card Mistakes

  • Never consider your credit limit to be your money-it’s borrowed money.
  • Regularly review your credit card statement for billing errors or fraud.
  • Try not to make only the minimum payment due, as this creates long-term interest and revolving debt.
  • Avoid applying for multiple cards in quick succession, as excessive hard inquiries can negatively impact your credit score.

Understanding the Revolving Credit Trap

You may be unknowingly trapped in long-term credit card debt due to the revolving credit system used by credit cards. The minimum payment required by credit card companies is typically between 2% and 5% of your balance, which seems reasonable but is intended to prolong repayment for years.

Always pay more than the minimum, maintain a low credit utilization rate, and strive to pay off your balance in full to avoid high APR charges and falling into the credit card debt trap. You can avoid long-term financial stress and safeguard your credit score by using revolving credit responsibly.

When you only make the minimum payment, the majority of your money goes toward credit card interest rather than lowering the actual balance, trapping you in debt while the bank makes money.

— Finsery Editorial Team

Frequently Asked Questions

Yes, you can withdraw money using a cash advance, but it’s expensive. Cash advances come with high fees, higher interest rates, and interest starts immediately. It’s best to use them only in emergencies.

There isn’t any one particular card that is necessarily the easiest to get with a high limit, because limits are based upon your credit score, income, and overall financial history. However, cards from banks with which you already have an account, or premium reward cards, often include higher starting limits if you have strong credit with stable income.

Using 90% of your credit card limit negatively affects your credit score because it significantly increases your credit utilization ratio, one of the major factors in credit scoring. It also signals high risk to lenders and may result in higher interest charges, lower chances of approval for future credit, and possible limit reductions by the issuer.

The minimum payment is the smallest amount you must pay to keep your account in good standing. Paying only the minimum leads to high interest costs and long-term debt.

Paying only the minimum amount due keeps your account active but leads to long-term interest and can trap you in revolving debt.

No, getting a credit card does not hurt your credit by itself. However, a hard inquiry during the application process might temporarily lower your credit score. Using the card responsibly, making payments on time, and keeping balances low will ultimately improve your credit score.